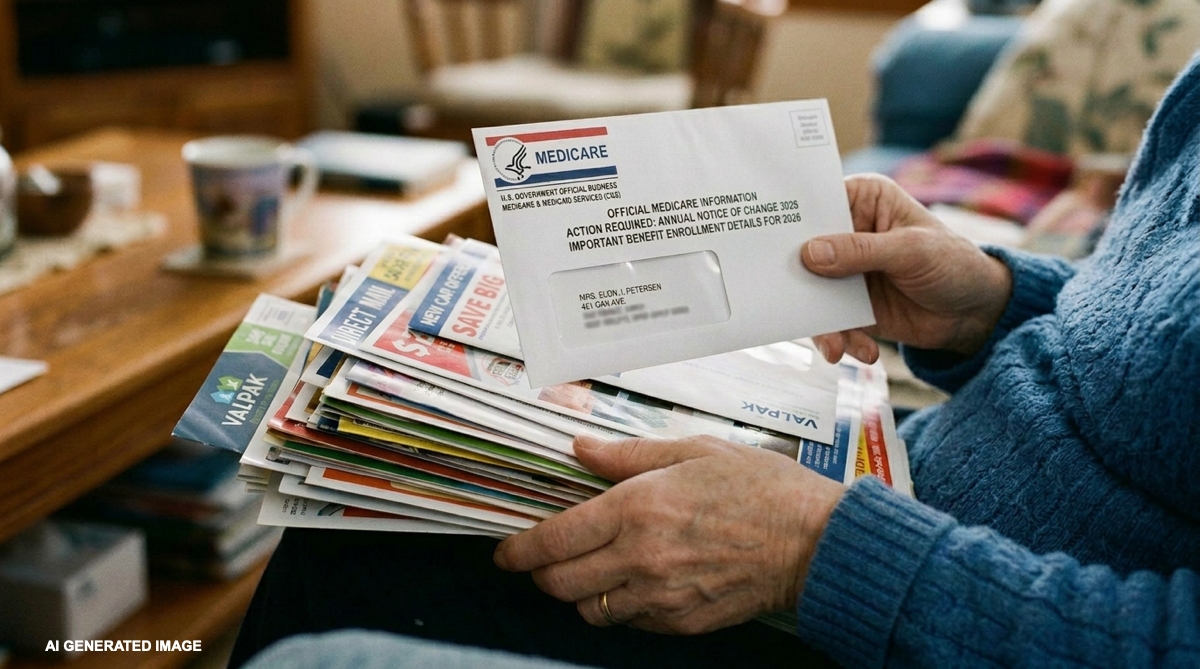
Every fall, if you're enrolled in a Medicare Advantage plan or a stand-alone Part D prescription drug plan, you'll receive an important piece of mail: the Annual Notice of Change, or ANOC. Many people glance at the envelope, assume it's routine paperwork, and tuck it away in a drawer, but this is a letter worth reviewing.
Your ANOC is your plan's official preview of what will change starting January 1 of the coming year. By law, plans must deliver it to you no later than September 30 each year, which gives you time to review it before Medicare's Annual Enrollment Period begins on October 15. Inside, you'll typically find details about premiums, drug coverage, copayments and coinsurance, provider networks, and any coverage changes starting January 1.
Why This Letter Deserves Your Attention
Many people assume that if you've been happy with your plan all year, then you don’t need to do anything and nothing will change. But Medicare Advantage and Part D plans are permitted to adjust their costs and coverage from one year to the next. The monthly premium might go up or down, a medication you've taken for years may move to a different cost tier or no longer be covered at all, or prior approval may now be required. A doctor or specialist you see regularly may no longer be part of the plan's network.
These changes do not require your permission and can significantly impact your coverage. Reviewing your ANOC carefully gives you a critical head start, allowing you to identify specific concerns or areas to address, such as network or formulary changes, before annual enrollment arrives. This ensures that when it comes time to sit down with us after October 1 for your Medicare review, you and your agent can focus on evaluating the aspects of your plan that you already know need your attention.
What Can Actually Change
The ANOC covers more ground than most people expect. Along with monthly premiums and annual deductibles, it can outline new copayment or coinsurance amounts for doctor visits, specialist care, and hospital stays. It will also show whether your medications have moved to a different cost tier, been removed from the formulary altogether, or gained a new requirement like prior authorization or step therapy. Provider and pharmacy networks can change, too, meaning a doctor or pharmacy you rely on today might not be included next year. Even the maximum amount you'd pay out of pocket in a year, and benefits like dental, vision, or hearing can be adjusted, expanded, or reduced. The plan may even add new, additional supplemental benefits in the coming year.
A Quick Example
Consider a longtime Medicare Advantage enrollee named Margaret, who was satisfied with her plan, didn’t open her ANOC, and let her enrollment automatically renew during annual enrollment. It wasn’t until January that she realized her monthly premium had gone up slightly, and more importantly, a maintenance medication she'd taken for years had moved to a higher cost tier. She also discovered that one of her regular specialists was no longer in the plan's network. Had she caught these changes in October, she would have had time to compare plans and talk with a licensed agent before the Annual Enrollment Period closed. But now she was locked into her plan for the rest of the year.
What to Do When Your ANOC Arrives
The envelope will likely be marked with something like "Important Plan Information” or may be labeled “Annual Notice of Change.” Open it and read through the entire letter. Many ANOCs include a side-by-side comparison of this year's plan details versus next year's. Pay close attention to four things in particular: your premium, your specific medications, the providers you see most often, and the benefits you use most or expect to use in the coming year. If anything has changed in a way that concerns you, that's your cue to explore other options. Starting on October 1, you can work with one of our licensed insurance agents to compare plans and prepare for Annual Enrollment from October 15 - December 7.
Common Mistakes to Avoid
The most common mistake is simply not opening the envelope, and assuming that because nothing has gone wrong this year, nothing will change next year. Another is reading only the first page and missing details buried further in, such as formulary or network changes. Some people miss the window and open it too late to take action during the Annual Enrollment Period, which runs October 15 through December 7. Others focus solely on the premium and overlook drug coverage or network changes, which can end up costing far more over the course of a year.
Free, Unbiased Help Is Available
You don't have to sort through your ANOC alone. Starting on October 1, we can walk you through the changes and help you weigh plans that may better fit your needs in 2027. If you'd like more immediate assistance, your State Health Insurance Assistance Program, known as SHIP, offers free resources to help you understand your notice. Either way, any changes you decide to make during the Annual Enrollment Period will take effect on January 1.
Conclusion
Your ANOC may look like just another piece of mail, but it's one of the most useful documents Medicare sends you all year. Reading it carefully, checking your premium, your medications, and your providers, and comparing your options can help you make sure you’ve got a plan that truly fits your needs. Don't throw it away, and don't let it sit unopened. A little attention each fall can go a long way toward protecting your healthcare and your budget in the year ahead.