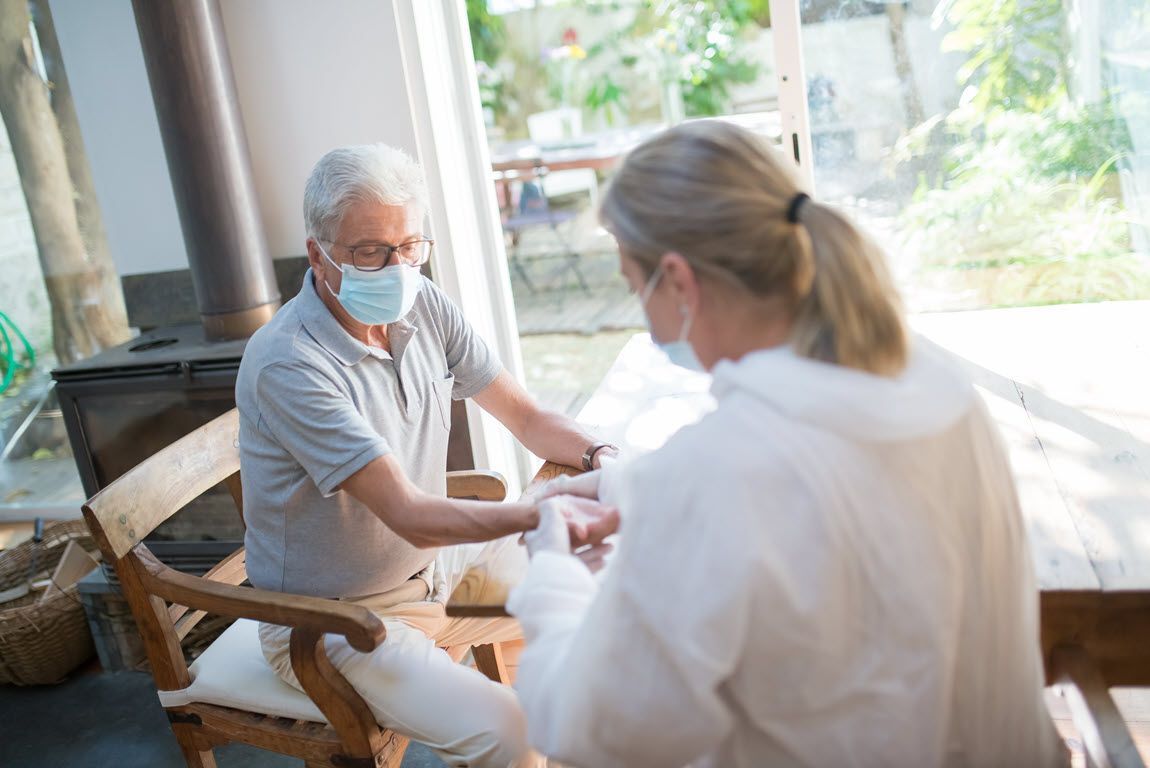
Most of us don't spend much time thinking about what would happen if a serious illness or injury left us needing help with everyday tasks. But it's one of the most important financial questions a family can face, and the time to think about it is before long-term care is needed. In other words, the time to think about it is
now.
Consider this… Assisted living facilities and nursing home care can cost upwards of $6,000 a month. Even in-home nursing care averages around $2,000 per month. If you needed that level of care for longer than a few months, where would that money come from?
For most families, the answer is painful. It comes from retirement savings. It comes from the inheritance you spent decades building. And sometimes, it comes from your children.
The Hidden Cost Nobody Plans For
Here's what surprises many people: health insurance, Medicare, and most other traditional coverage are simply not designed to pay for long-term personal care. That includes help with bathing, dressing, getting around the house, and managing daily life. Medicare may cover short-term skilled care under very specific conditions, but it does not cover ongoing personal or custodial care. Medicaid may help in some situations, but qualifying typically requires spending down most of your assets first.
That means, without a plan, the financial burden lands directly on you and your family.
And it's not only a financial burden. When a loved one needs care and no plan is in place, family members often step in to fill the gap themselves.
A spouse puts their own health on the back burner. An adult child cuts back work hours or dips into their own savings. Relationships that were built on love and good memories can become strained under the weight of physical, emotional, and financial stress that nobody was prepared for.
The Ripple Effect on Your Legacy
You've likely worked hard to build something for the people you love, like a retirement that provides security, or savings you hoped to pass on to your children.
A long-term care event, without proper coverage, can erode all of that quickly. It's not uncommon for families to see years of savings depleted within a relatively short period of time when care costs are paid entirely out of pocket. What was meant to be a legacy quietly disappears simply because long-term care wasn't part of the conversation.
The earlier you address this, the better positioned you are. Purchasing a policy while you're younger and healthier typically means lower premiums over the life of the policy. Waiting can mean higher costs or, in some cases, limited options.
What Long-Term Care Insurance Can Do
A long-term care insurance policy can help cover a range of services, including in-home care, adult day programs, assisted living, memory care, skilled nursing facilities, hospice services, and respite care for family caregivers. Many comprehensive policies also cover in-home therapies, help with daily activities like meal preparation and housekeeping, and even home modifications such as wheelchair ramps.
For people who want to stay in their own home, the right coverage can make that possible. For families who want to be involved in a loved one's care without being financially or physically overwhelmed by it, coverage creates breathing room.
Every policy is different, and the right plan depends on your needs, your health, and your goals. That's a conversation worth having sooner rather than later.
It's More Than Insurance. It's Protection for Everyone You Love.
Long-term care insurance isn't about expecting the worst. It's about making sure that if something happens, your family has choices. You have choices. The savings you worked to build stay intact. The legacy you wanted to leave behind remains yours to give.
Long-term care insurance is an investment in your family's future.
Ready to learn more? Give us a call and let's talk about what long-term care planning could look like for you and your family.